A good credit score can make it easier to qualify for loans and credit cards in India. Banks and financial institutions use credit scores, along with other financial details, to assess how responsibly a person has managed credit in the past.
If you are planning to apply for a home loan, personal loan, car loan, or credit card, understanding your credit score is important. A higher score generally improves your chances of getting approved and may help you qualify for better loan terms.
In this guide, we will explain what a good credit score means in India, how CIBIL scores work, which factors affect your score, and how you can check and improve it.
1. Understanding Credit Scores in India
A credit score is a three-digit number that represents your credit history and repayment behaviour. Lenders use it to assess the risk of lending money to you.
In India, credit scores are provided by credit information companies (CICs), also known as credit bureaus. The four major credit information companies are:
- TransUnion CIBIL
- Experian
- Equifax
- CRIF High Mark
Each credit bureau maintains credit information received from banks and other financial institutions. The scoring models may differ, so your score can vary between credit bureaus.
What Is a CIBIL Score?
A CIBIL Score is a three-digit number that represents your credit history based on information in your CIBIL report. It ranges from 300 to 900. Generally, a higher score indicates a stronger credit history and better repayment behaviour.
According to CIBIL’s official credit score guidance, a score above 700 is generally considered good. However, lenders may have different eligibility requirements depending on the loan product and their internal policies.
2. What Is a Good Credit Score in India?
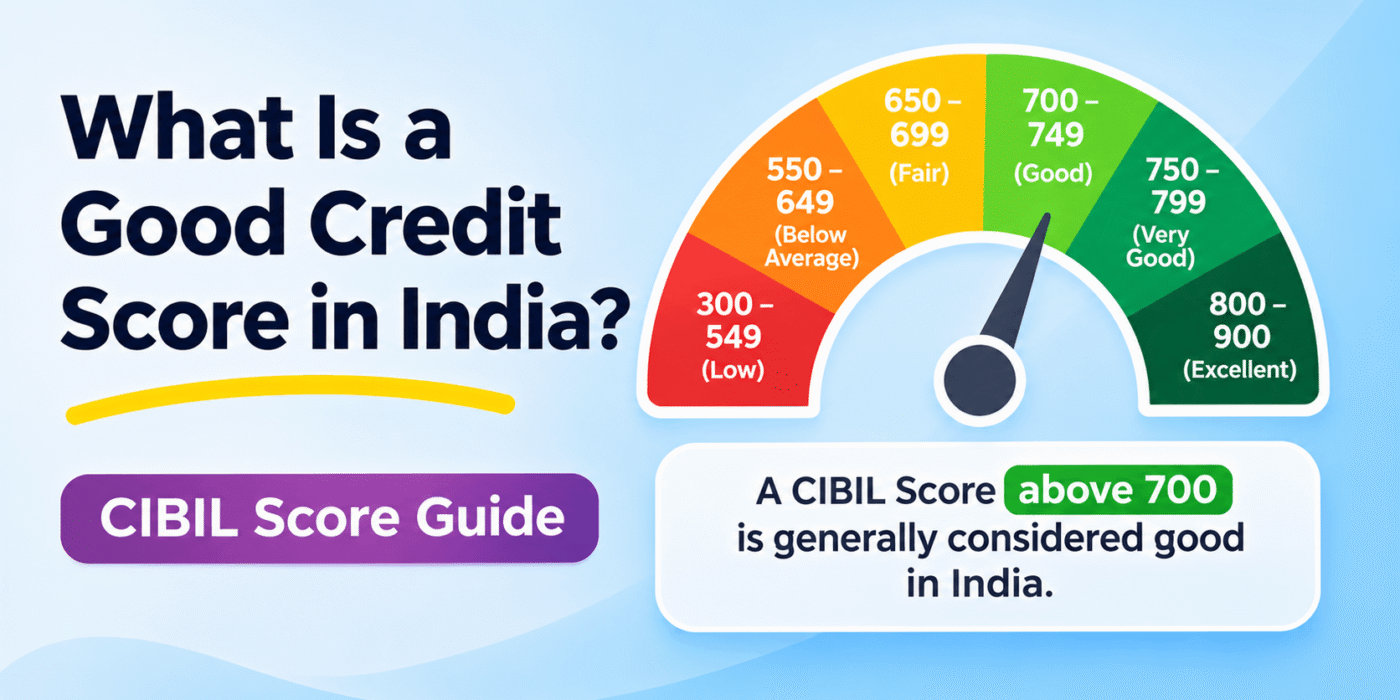
In India, a CIBIL Score above 700 is generally considered good. A score of 750 or higher is often viewed as a strong credit profile by lenders, although approval is never guaranteed based on the score alone.
The following table provides a simple, indicative way to understand common CIBIL score ranges. These labels are for general guidance, not an official universal classification used by every lender.
| Credit Score Range | General Interpretation |
|---|---|
| 300–549 | Low |
| 550–649 | Below average |
| 650–699 | Fair |
| 700–749 | Good |
| 750–799 | Very good |
| 800–900 | Excellent |
Remember that these categories are indicative. Different lenders may use different score cut-offs, and they also consider your income, existing debt, employment or business stability, and other details when reviewing an application.
3. Why Is a Good Credit Score Important?
Maintaining a good credit score can be beneficial when you need financial assistance. Here are some important reasons to maintain a healthy credit profile.
1. Better Chances of Loan Approval
Lenders review your credit score and repayment history when you apply for a loan. A stronger credit profile can improve your chances of approval, subject to the lender’s eligibility criteria.
2. Potentially Better Interest Rates
Some lenders offer more favourable interest rates to applicants with stronger credit profiles. A good score may help you negotiate better loan terms, although the final rate also depends on the lender and your overall financial situation.
3. Improved Credit Card Eligibility
A good credit score can improve your chances of qualifying for certain credit cards. However, card issuers may also consider your income, existing credit obligations, and other eligibility requirements.
4. Greater Financial Flexibility
A healthy credit history can make it easier to access credit when you need it. Maintaining a good score can therefore help you prepare for future financial requirements.
4. Factors That Affect Your Credit Score
Several factors influence your credit score. Understanding them can help you develop better financial habits and maintain a healthy credit history.
1. Payment History
Your payment history is an important part of your credit profile. Missing credit card payments or delaying loan EMIs can negatively affect your score.
Try to pay all your EMIs and credit card bills before their due dates. Setting up payment reminders or automatic payments can help you avoid missed payments.
2. Credit Utilization Ratio
Credit utilization refers to how much of your available credit limit you are using. For example, if your credit card limit is ₹1,00,000 and your outstanding balance is ₹30,000, your credit utilization is 30%.
Keeping your credit utilization low is generally advisable. Avoid using most of your available credit limit regularly, as high utilization may indicate greater dependence on borrowed money.
3. Length of Credit History
The length of your credit history refers to how long you have maintained credit accounts. A longer history of responsible borrowing and timely repayments can help demonstrate that you manage credit consistently.
Closing an old credit card account may affect your overall credit profile, depending on your circumstances. Consider the impact before closing accounts that you have managed responsibly.
4. Credit Mix
Your credit mix refers to the different types of credit accounts you have, such as secured loans and unsecured loans.
A healthy mix may contribute positively to your credit profile. However, you should not take unnecessary loans simply to increase the variety of credit accounts you hold.
5. New Credit Applications and Enquiries
When you apply for a loan or credit card, the lender may access your credit report. This is recorded as a credit enquiry.
Applying for several credit products within a short period can create multiple enquiries and may affect your score. Apply for new credit only when you genuinely need it.
For more information, see CIBIL’s guidance on credit scores and improving credit history.
5. How to Check Your Credit Score in India
Checking your credit score regularly helps you understand your financial position and identify possible errors in your credit report.
You can check your credit information through the following methods:
1. Check Through Credit Bureau Websites
You can visit the official websites of India’s credit information companies to access your credit score and report:
Each bureau may offer different services and subscription options. Check the official website for the current process and available free or paid services.
2. Use Your Bank or Credit Card Provider
Some banks and financial institutions provide credit score information through their mobile applications or internet banking services. Check with your bank to see whether this facility is available.
3. Get Your Free Annual Credit Report
The Reserve Bank of India requires credit information companies to provide individuals with one free full credit report, including the credit score, once per calendar year. You can access this report through the respective credit bureau after completing its identity verification process.
Read the RBI’s financial awareness guidance on credit scores for more information about free annual credit reports.
6. Tips to Improve Your Credit Score
If your credit score is lower than you expected, do not worry. Building a stronger credit profile takes time, but consistent financial habits can help.
1. Pay EMIs and Credit Card Bills on Time
Always try to pay your loan EMIs and credit card bills before the due date. Even a small payment delay can affect your repayment history.
2. Keep Credit Utilization Low
Avoid using most of your available credit limit. Keeping outstanding balances under control can help maintain a healthier credit profile.
3. Review Your Credit Report for Errors
Check your credit report for incorrect personal details, unfamiliar accounts, incorrect outstanding balances, or payments that have not been updated properly.
If you find an error, raise a dispute with the relevant credit bureau and contact the financial institution that reported the information.
4. Avoid Applying for Too Many Loans
Multiple credit applications within a short period can result in several hard enquiries. Apply for credit selectively instead of submitting applications to many lenders at once.
5. Maintain a Responsible Credit Mix
Manage your existing secured and unsecured credit accounts responsibly. Do not borrow money unnecessarily just to create a particular credit mix.
6. Monitor Joint and Guaranteed Accounts
If you are a co-borrower, guarantor, or joint account holder, remember that missed payments on those accounts may affect your credit history. Review these accounts regularly.
7. How to Maintain a Good Credit Score
Once you have achieved a good credit score, maintaining it is just as important. Follow these practices to keep your credit profile healthy:
- Pay on time: Make all loan and credit card payments before their due dates.
- Control spending: Keep credit card balances within a manageable limit.
- Check your credit report: Review your report periodically for errors or unfamiliar activity.
- Apply for credit carefully: Avoid unnecessary loan and credit card applications.
- Manage existing accounts: Keep track of outstanding loans, credit cards, and joint accounts.
- Be consistent: Responsible credit behaviour over time is more useful than trying to improve your score through quick fixes.
8. Common Credit Score Myths Explained
There are several misconceptions about credit scores. Let’s look at a few common myths and the facts behind them.
Myth 1: A Higher Income Automatically Means a Higher Credit Score
Fact: Income is not the same as credit history. A higher salary does not automatically increase your credit score. Your repayment behaviour and credit account information are important factors in determining your score.
Myth 2: Checking Your Own Credit Score Reduces It
Fact: Checking your own credit score through a credit bureau or an authorized consumer service is generally treated as a self-check and does not lower your score. A lender’s credit enquiry when you apply for credit is different.
Myth 3: You Can Repair Your Credit Score Overnight
Fact: There is no reliable shortcut to building a strong credit history. Improving your score usually requires consistent repayments, responsible credit usage, and time. Be careful of services that promise guaranteed or instant credit score improvements.
Myth 4: Closing Every Credit Card Improves Your Score
Fact: Closing a credit card does not automatically improve your credit score. It may change your available credit limit and affect your credit utilization. Consider your overall credit profile before closing an account.
Conclusion
A good credit score in India is generally considered to be above 700, while a score of 750 or higher is often viewed as a strong credit profile. However, every lender has its own eligibility requirements, and your score is only one part of the loan approval process.
To maintain a healthy credit score, pay your EMIs and credit card bills on time, keep credit utilization under control, avoid unnecessary credit applications, and review your credit report regularly.
Building a good credit history takes time. Consistent and responsible financial behaviour is the best way to maintain a strong credit profile and improve your chances of accessing credit when you need it.